National Life Insurance Family Savings and Income Insurance Plan: Benefits & Features
A well-planned family budget is not just about paying today's bills. It is also about preparing for tomorrow's responsibilities, building savings habits, and understanding how life insurance may contribute to long-term financial planning.
National Life Insurance PLC lists the Family Savings & Income Insurance Plan (with profit) among its insurance products in its 2024 annual report. However, the plan's exact payment schedule, eligibility criteria, benefits, and policy conditions need to be confirmed through the company's current official documentation before readers make financial decisions.
When the Monthly Budget Meets the Family's Future
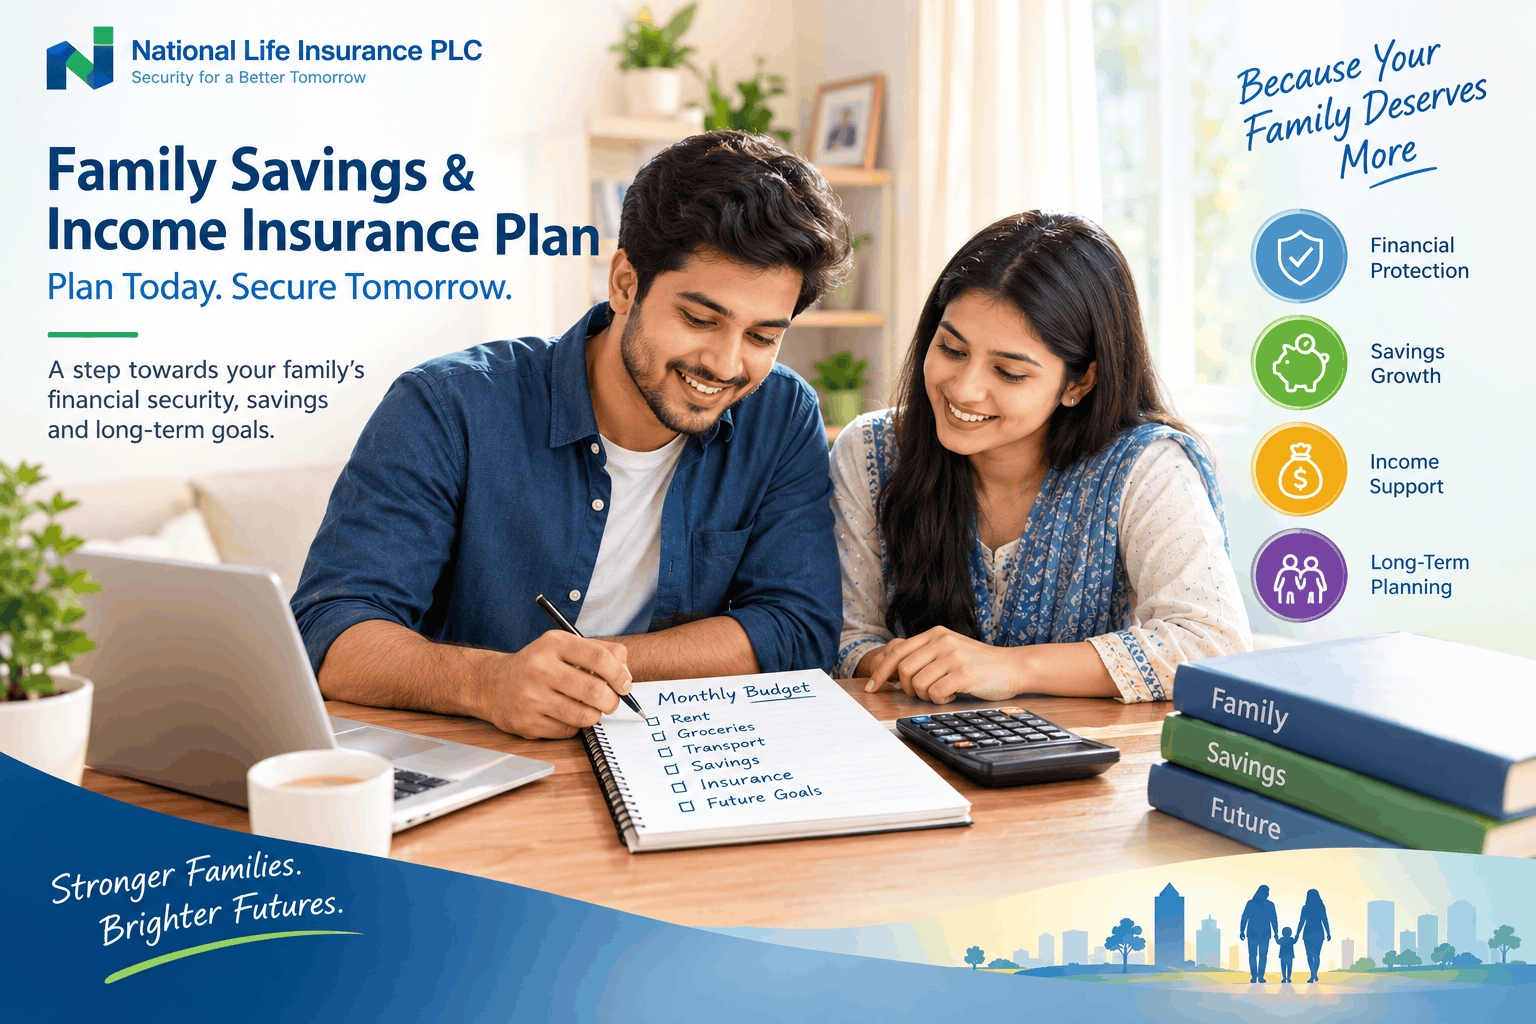
It was Sunday evening, and Rafi and Nusrat were doing something they had promised to do for weeks: reviewing their household budget.
Rafi worked in a private company in Dhaka. Nusrat had recently started her career. Between rent, groceries, transport, family responsibilities, and the occasional invitation to a wedding, their monthly salary seemed to have several appointments before it even arrived.
"We should save more this month," Nusrat said, opening a notebook.
"Absolutely," Rafi replied. "Let's start after we order dinner."
Nusrat looked at him. "That's exactly how our savings plan became a food delivery plan."
They laughed, but the conversation raised an important question. If they wanted to build a family, support their parents, and prepare for future expenses, would saving whatever remained at the end of the month be enough?
Their situation is fictional, but the financial question is familiar to many young professionals and couples in Bangladesh.
Saving money is important. However, families may also need to consider financial protection, long-term commitments, and what could happen to their plans if circumstances change.
This is where understanding life insurance becomes useful. One product listed by National Life Insurance PLC is the Family Savings & Income Insurance Plan (with profit).
Understanding its documented terms is the first step toward deciding whether it deserves a place in a family's financial plan.
🔷 What Is the National Life Insurance Family Savings and Income Insurance Plan?
The National Life Insurance Family Savings and Income Insurance Plan is a named insurance product listed in the company's published 2024 annual report. The report identifies it as a plan "with profit," but the precise benefit structure, payment arrangements, and conditions should be confirmed from the current policy documents.
For a family researching this plan, three questions matter:
- What insurance protection does the policy provide?
- How are savings or income-related benefits structured?
- What payments, conditions, and commitments apply to the policyholder?
These questions are more useful than choosing a policy based on its name alone.
The words family, savings, and income may sound reassuring, but the actual policy wording determines what a customer is entitled to receive. It is important to distinguish a product's name from its contractual benefits.
For Rafi and Nusrat, that would mean understanding the plan before including it in their monthly budget. They would need clear answers about premiums, policy duration, and the benefits payable under different circumstances.
A little research now can help prevent considerable confusion later.
🔷 Why Do Families Need a Structured Savings and Insurance Plan?
A structured financial plan helps families assign money to specific responsibilities instead of relying entirely on whatever remains after monthly spending.
For example, a young couple might want to prepare for:
- Future children's education.
- Housing expenses and household improvements.
- Support for parents or other dependants.
- Long-term financial goals.
- Financial responsibilities that may continue if the earning member dies.
These goals require different approaches. An emergency fund, ordinary savings, and life insurance serve different purposes, even though all may contribute to a family's financial planning.
🔸 Savings create financial discipline
Regular saving encourages people to set aside money for future needs. A consistent approach can help make long-term goals feel more manageable.
Rafi and Nusrat could begin by recording their essential expenses, identifying realistic savings targets, and deciding how much they can comfortably set aside each month.
They would also need to account for irregular expenses, such as medical bills, family occasions, and home repairs. These expenses have an annoying habit of appearing without consulting the household budget first.
🔸Insurance addresses a different need
Life insurance is designed to provide financial benefits when the events specified in a policy occur, subject to its terms and conditions.
Depending on the product, these benefits may support eligible beneficiaries after the insured person's death or provide benefits under specified survival or maturity conditions.
Not every policy offers the same combination of protection and savings. That is why families should examine the actual product rather than assume all life insurance plans work alike.
🔷 How Does the Family Savings and Income Insurance Plan Work?
The exact operation of National Life Insurance PLC's Family Savings & Income Insurance Plan should be confirmed through its current official policy documents. Publicly available company information identifies the plan as a product with profit, but the information reviewed for this article does not establish its detailed premium schedule, duration, eligibility rules, or income-payment structure.
Before making a decision, a prospective policyholder should understand several basic elements.
🔸 Premium payments
A premium is the amount paid to maintain an insurance policy according to its contractual requirements.
Ask the company about the premium amount, payment frequency, available payment methods, and consequences of missed or delayed payments.
The important question is not simply whether a premium looks affordable today. It is whether the household can reasonably maintain the commitment alongside essential expenses and other savings goals.
🔸Policy term
The policy term is the period specified in the insurance contract. Its length can affect the timing of payments, the period of coverage, and the conditions under which benefits become payable.
Ask which terms are available for this particular plan and whether any age-related requirements apply.
🔸Income and maturity benefits
An income benefit generally refers to money payable under specified policy conditions, while a maturity benefit is an amount that may become payable when a policy reaches its contractual maturity, provided the applicable conditions are met.
These terms should not be interpreted as a promise that every insurance policy pays regular income or a maturity amount.
For this plan, ask National Life Insurance PLC whether income payments are available, when they become payable, how maturity benefits are calculated, and which conditions apply.
🔷 What does "with profit" mean?
The phrase indicates that a policy is designated as a with-profit product. However, the label alone does not establish the amount, timing, or guaranteed status of any bonus or other payment.
Ask for a written explanation of how profits or bonuses are determined, whether any amounts are guaranteed, and which figures are illustrative rather than contractual.
That distinction helps families plan using documented information instead of optimistic assumptions.
🔷 What Are the Potential Benefits and Features?
The most responsible way to assess the Family Savings and Income Insurance Plan is to separate its documented features from the possible value those features might provide.
The company's 2024 annual report lists the plan as an insurance product with profit. Detailed terms should be verified before making claims about specific payouts or eligibility.
Here are the main areas worth investigating.
1. A product to consider in family financial planning
A family-oriented insurance product may be relevant to people who are exploring ways to organise their financial responsibilities.
For Rafi and Nusrat, the starting point would be to identify their priorities: maintaining emergency savings, supporting their parents, and preparing for future family expenses.
They could then assess whether this particular plan's documented coverage and payment structure match those priorities.
The plan's name alone is not sufficient evidence that it meets every family need.
2. Savings-related planning
Because the product is named the Family Savings & Income Insurance Plan, people researching it may reasonably want to understand its savings-related structure.
However, the amount payable, any accumulation mechanism, and the conditions for receiving benefits must come from the policy documents.
Ask for a written illustration showing applicable premiums, benefits, payment dates, and the assumptions used in any projections.
3. Understanding the income component
The word income may attract people looking for predictable financial support at a particular stage of life.
Before relying on this plan for household income, confirm whether it provides periodic payments, when those payments begin, how long they continue, and whether they depend on specific conditions.
If regular income is not contractually provided in the manner a family expects, the plan may not meet that particular objective.
4. A potential role in long-term financial preparation
Long-term financial planning involves more than choosing an insurance policy. Families also need to consider liquidity, affordability, financial obligations, and changing circumstances.
A policy may form one part of that wider plan if its actual terms suit the household's needs.
The goal is not to collect financial products. It is to make informed decisions that work together.
🔷 How Can Families Assess Whether the Plan Suits Them?
Imagine Rafi and Nusrat reviewing the plan after their Sunday budgeting session.
Instead of immediately deciding whether to purchase it, they make a list of questions. This approach gives them a practical way to evaluate the plan without relying on assumptions.
🔸Start with a realistic household budget
Calculate essential monthly expenses before deciding how much money could be committed to an insurance premium.
Include housing, food, transport, education where applicable, family support, existing debt payments, and regular savings.
Also consider whether an emergency fund is available for unexpected expenses.
A long-term insurance commitment should not leave the household unable to meet basic needs.
🔸 Match the policy to a specific goal
Ask what the plan is intended to help you achieve.
Your objective might involve family protection, a future financial milestone, or a particular income requirement. The relevant policy benefits should match that objective.
If the plan's payment schedule does not align with the intended goal, another financial arrangement or a combination of approaches may be more appropriate.
🔸 Review the policy conditions carefully
Before signing anything, understand:
- Who is eligible to apply.
- What information and documents are required.
- How premiums are calculated and paid.
- Which benefits are guaranteed and which are conditional.
- What exclusions, waiting periods, or other limitations apply, if any.
- What happens if premiums stop or the policy is surrendered.
- How claims are submitted and assessed.
- How beneficiaries are designated and updated.
These are questions to verify, not assertions that every listed condition necessarily applies to this product.
🔸 Consider future affordability
Your circumstances may change after marriage, the arrival of children, a job change, or an unexpected expense.
Consider whether you could maintain the premium if your income temporarily decreased. Ask what options are available if you cannot continue paying.
A policy that looks manageable today should also be evaluated against foreseeable changes in family responsibilities.
🔷 What Should You Ask National Life Insurance PLC Before Applying?
The company provides official product information and customer contact channels through its website. Its published contact information includes the call centre number 16749 and its Dhaka head office.
Before making a commitment, ask for the latest brochure and full policy terms for the Family Savings & Income Insurance Plan.
Useful questions include:
- What are the minimum and maximum entry ages?
- What policy terms and premium payment frequencies are available?
- What is the minimum premium or sum assured, if applicable?
- Does the plan provide periodic income, a maturity benefit, or both?
- How are bonuses calculated, and which benefits are guaranteed?
- What happens if the policyholder dies during the policy term?
- Are additional benefits available, and what do they cost?
- What are the surrender, lapse, and revival conditions?
- Which documents are required to apply and make a claim?
Request written answers wherever possible. If a representative provides an example of potential benefits, ask which amounts are guaranteed and which depend on assumptions or future conditions.
You can explore the company's official website at National Life Insurance PLC and use its published contact channels to request product-specific information.
🔷 Frequently Asked Questions
🔸 What is the National Life Insurance Family Savings and Income Insurance Plan?
It is an insurance product listed by National Life Insurance PLC in its 2024 annual report as the Family Savings & Income Insurance Plan (with profit). Its specific benefits, premium requirements, and conditions should be confirmed through current official policy documentation.
🔸 Does the plan provide regular income?
The product name includes the word "Income," but that alone does not confirm the payment schedule. Ask National Life Insurance PLC whether periodic payments are included, when they become payable, and what conditions apply.
🔸 Is the plan suitable for newly married couples?
It may be worth investigating if a couple is considering long-term financial planning. Suitability depends on their budget, financial responsibilities, insurance needs, and the plan's actual contractual terms.
🔸 How much premium must I pay?
The current premium requirements for this specific plan should be obtained from the company. Ask for a personalised quotation based on the applicable eligibility criteria and selected policy terms before deciding whether the commitment is affordable.
🔸 Are returns or bonuses guaranteed?
Do not assume that all bonuses, projected benefits, or future payments are guaranteed. Request written clarification identifying guaranteed amounts, conditional benefits, and the assumptions used in any illustration.
🔸 Can I stop paying premiums whenever I want?
The consequences of stopping premium payments depend on the policy contract. Before applying, review the rules covering missed payments, policy lapse, revival, and surrender, including any financial consequences.
🔸 Where can I get official information about the plan?
Visit National Life Insurance PLC's official website or contact its published call centre at 16749 to ask for the latest brochure, policy wording, and application requirements.
🔷 Conclusion: Make Your Family's Financial Plan a Thoughtful One
Later that Sunday evening, Rafi and Nusrat returned to their budget notebook. They had not solved every future financial question, but they had agreed on something important: their financial decisions deserved more attention than whatever happened to remain in the bank account at the end of the month.
They decided to review their expenses, build their savings gradually, and investigate insurance options by reading the actual policy documents before committing to anything.
For families considering the National Life Insurance Family Savings and Income Insurance Plan, the same approach makes sense. The product appears in National Life Insurance PLC's published list of insurance offerings, but its current contractual details must guide any decision.
Before applying, request the latest official documentation, confirm the premium and benefit structure, and make sure the commitment fits your family's circumstances.
Explore National Life Insurance PLC's official website at nlibd.com or contact its call centre at 16749 to clarify the plan's terms and available benefits. An informed decision begins with clear answers, a realistic budget, and a plan that makes sense for your family's needs.
← Back to Insights
NLI Archive / 2026
Trending Analysis
National Life Insurance Family Savings and Income Insurance Plan
N
NLI Editorial
© National Life Insurance Co. Ltd.
Share:
FB
LN