Monthly vs. Yearly Insurance Premium: Which Payment Option Is Better for You?
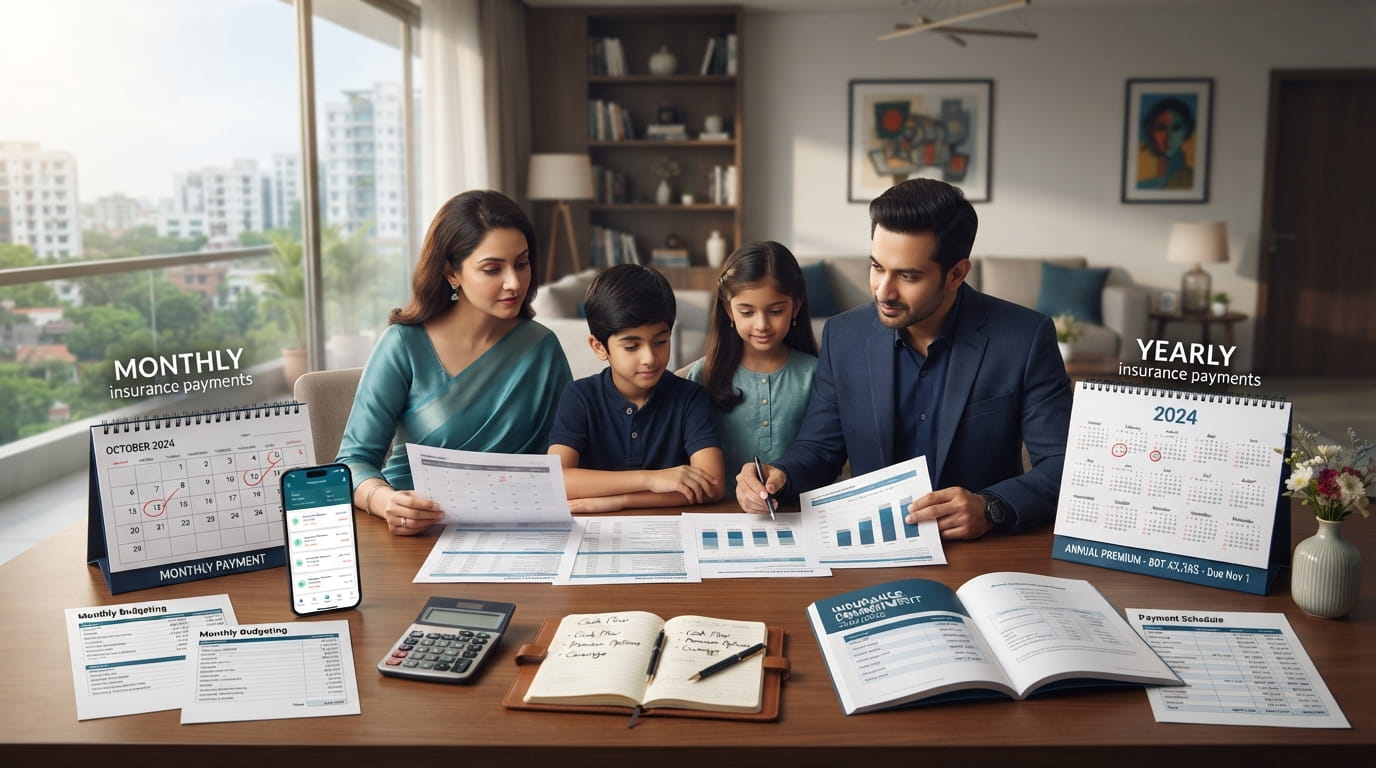
Imagine a family in Dhaka where both parents have stable incomes. Their children's school fees are paid on time, investments are running, household expenses are under control, and they regularly set money aside for future goals.
Now they are considering life insurance.
One question comes up almost immediately: Should we pay the insurance premium every month, or would a yearly payment be better?
There is no single answer for every family.
For some people, a monthly insurance premium feels easier because the payment fits naturally into their regular household budget. For others, a yearly insurance premium is more convenient because they prefer to handle the entire insurance expense once a year.
So, when comparing monthly vs. yearly insurance premium, the real question is not simply which one is “better.” The better option depends on your income pattern, cash flow, financial habits, family responsibilities, and the specific terms of the insurance policy you are considering.
This guide explains the difference in simple terms so you can make a more informed decision for yourself and your family.
🔷 Is Monthly or Yearly Insurance Premium Better?
Neither monthly nor yearly insurance premium is universally better. The right payment frequency depends on your cash flow, budgeting habits, financial commitments, and the specific policy terms. Monthly payments may help spread expenses throughout the year, while yearly payments may suit people who prefer managing one larger annual financial commitment.
The important point is to compare the total premium payable, payment terms, available options, and policy benefits before making a decision.
🔷 What Is a Monthly Insurance Premium?
A monthly insurance premium means you make your required insurance payment on a monthly schedule, subject to the payment options and terms of the particular policy.
For someone with a regular monthly salary, this arrangement can feel familiar.
You receive your income, manage household expenses, pay school or university costs, contribute to investments, handle utility bills—and then allocate a planned amount toward insurance.
In simple words, instead of thinking about insurance as one large yearly expense, you treat it as a recurring part of your monthly financial plan.
🔷 Who may prefer monthly insurance payments?
A monthly insurance payment may be worth considering if you:
🔸prefer predictable monthly expenses
🔸receive regular monthly income
🔸want to spread an insurance expense across the year
🔸already follow a monthly household budget
🔸prefer smaller recurring payments rather than one large payment
🔸want insurance to become part of your regular financial routine
However, monthly payment also means you need to stay organized. There are more payment dates to remember compared with a yearly arrangement.
That may sound small, but anyone managing school fees, credit cards, investments, utility bills, subscriptions and household expenses knows that “just one more payment date” can sometimes become surprisingly easy to forget.
🔷 What Is a Yearly Insurance Premium?
A yearly insurance premium means the premium is paid once each year according to the policy's applicable terms.
This approach may appeal to people who prefer annual financial planning.
For example, an established business owner might review personal insurance, investments, tax-related planning, children's education funds and other major financial commitments once or twice a year.
For that person, handling insurance as one planned annual expense may be simpler than managing recurring monthly payments.
🔷 Who may prefer yearly insurance payments?
A yearly insurance payment may suit someone who:
🔸 prefers fewer payment dates
🔸plans major financial expenses annually
🔸has enough liquidity for a larger one-time payment
🔸likes to review financial commitments once a year
🔸prefers simpler payment tracking
🔸receives income in larger periodic amounts
But there is one important consideration: you need to plan for the annual payment in advance.
If a large payment arrives at a time when you have unexpected business expenses, school fees, investment commitments or other financial priorities, the annual payment may feel less comfortable.
🔷 Monthly vs. Yearly Insurance Premium: What Is the Practical Difference?
At first glance, the difference seems simple: one payment schedule is monthly and the other is yearly.
But the practical difference is really about cash-flow management.
Suppose a fictional family needs to plan for an annual insurance expense of BDT 120,000. If the policy's terms allowed an equivalent monthly schedule of BDT 10,000, the family's cash-flow experience would be very different even though the illustrative annual amount is the same.
This is only an example for understanding payment frequency. It is not an actual National Life Insurance premium quotation.
The monthly approach may feel easier because the expense is distributed across the year.
The yearly approach may feel easier because the family deals with the expense only once.
The key is to look at your financial life—not someone else's.
🔷 Monthly Insurance Premium: Potential Advantages
1. Smaller individual payments
A monthly payment can make a planned insurance expense feel more manageable because you are not arranging the entire year's payment at once.
For people who think in terms of monthly budgets, this can be psychologically and practically convenient.
2. Easier monthly cash-flow planning
If your salary arrives every month, you may already divide your income among:
🔸household expenses
🔸children's education
🔸savings
🔸investments
🔸transportation
🔸utilities
🔸lifestyle expenses
🔸emergency savings
🔸insurance
A monthly insurance payment can fit naturally into this structure.
3. Useful for regular-income earners
A senior executive receiving a predictable monthly salary may find it convenient to incorporate insurance into the monthly financial plan.
The same idea can apply to families at different income levels. The size of the income may change, but the basic budgeting principle remains the same: choose a payment rhythm that fits the way money enters and leaves your household.
4. May support disciplined budgeting
Some people are simply better at managing smaller recurring expenses than large annual commitments.
If that sounds like you, a monthly insurance payment may feel more natural.
🔷 Monthly Insurance Premium: Potential Considerations
Monthly payment is not automatically the right choice.
You should consider:
🔸Can you consistently remember the payment dates?
🔸Does the policy allow the payment frequency you want?
🔸Are there any policy-specific conditions related to payment frequency?
🔸What is the total amount payable over the relevant period?
🔸Would recurring payments become difficult during months with unusually high expenses?
Your insurance advisor can help explain the exact payment terms applicable to the policy.
🔷 Yearly Insurance Premium: Potential Advantages
1. Fewer payment dates
This is one of the simplest benefits.
Instead of managing multiple payment events throughout the year, you plan for one annual insurance payment according to the policy terms.
For someone who dislikes keeping track of many recurring expenses, that can be convenient.
2. Easier annual financial planning
High-income families often have several major financial decisions to make throughout the year.
A family may review investments, children's education planning, property expenses, business commitments and insurance during an annual financial review.
A yearly insurance payment can fit naturally into this type of planning.
3. Convenient for people with larger periodic income
Consider a business owner in Chattogram.
Rahim runs an established business and his household income does not always arrive in exactly the same pattern every month. Some months are strong; some months require more business reinvestment.
For Rahim, an annual payment may be easier if he can comfortably reserve the required amount in advance.
The lesson is not “business owners should always pay yearly.”
The lesson is: your income pattern matters.
4. Simpler record keeping
Some people prefer to review one major insurance payment in their annual financial records rather than manage many recurring transactions.
Again, convenience is personal.
🔷 Yearly Insurance Premium: Potential Considerations
The biggest consideration is liquidity.
A yearly insurance payment requires you to have the necessary amount available when the payment becomes due.
Before choosing this approach, ask yourself:
🔸Can I comfortably reserve the annual amount?
🔸Will this payment compete with another major financial commitment?
🔸Do I have an emergency fund?
Is my income stable enough to plan the annual payment?
🔸Would I feel more comfortable dividing the expense across the year?
If arranging the full annual amount would create financial pressure, a different payment frequency may be more suitable—if that option is available under the policy terms.
🔷 Does Monthly or Yearly Insurance Cost More?
This is one of the most important questions when comparing monthly vs. annual insurance premium.
The safe answer is: it depends on the specific policy and insurer's terms.
Do not assume that yearly payment is automatically cheaper.
Likewise, do not assume that monthly payment is automatically more expensive.
When comparing insurance premium cost, look beyond the size of each individual payment.
Consider:
🔸the total premium payable
🔸payment frequency
🔸applicable charges, if any
🔸policy-specific payment conditions
🔸available payment modes
🔸coverage and benefits
🔸the duration of the policy
🔸any other terms stated in the policy documents
For example, imagine an illustrative policy where the total annual premium is BDT 120,000.
If the available payment structure were exactly equivalent, you might see an illustrative calculation such as:
BDT 120,000 ÷ 12 = BDT 10,000 per month.
But this calculation does not mean that an actual insurance policy will necessarily use this structure.
It is only a mathematical example to explain the difference between payment frequency and total annual cost.
For an actual policy, always ask the insurer or advisor for the applicable premium schedule.
🔷 A High-Income Family in Dhaka: Which Option Could Make Sense?
Consider another fictional example.
Sadia and her husband live in Dhaka. They have two children. Their household income is strong, but they also have several financial commitments: children's education, investments, home expenses, travel, retirement planning and an emergency fund.
They are considering life insurance as part of their long-term family financial planning.
Sadia prefers monthly budgeting because she tracks household cash flow closely.
Her husband prefers yearly payments because he likes to organize major financial commitments during their annual financial review.
Who is right?
Actually, both preferences can be reasonable.
If a suitable policy provides both payment options, the couple should compare the actual terms and decide which structure fits their cash flow and financial habits.
The important lesson is that income level alone does not determine the best payment option.
Even a high-income family can prefer monthly payments if they value cash-flow flexibility.
🔷 What About a Family in Rajshahi?
Now consider a fictional family in Rajshahi.
Hasan has a stable professional income. His family has regular household expenses and is planning for his children's future education.
He likes simple financial systems.
Instead of tracking many recurring payment dates, he prefers to set aside money for major annual financial commitments.
For Hasan, a yearly insurance payment may feel easier—provided the required amount can be comfortably reserved without disturbing emergency savings or other priorities.
Someone else with exactly the same income could make a different decision.
That is why the best insurance payment option is personal.
🔷 What About a Business Owner With Irregular Cash Flow?
Business owners may face another challenge.
A business can have strong months and weaker months. Cash may also be needed for inventory, employees, expansion, taxes, suppliers or unexpected business requirements.
Imagine a successful entrepreneur in Chattogram.
He can afford his insurance premium, but he does not want a large annual financial commitment to arrive at a time when business liquidity is tight.
In that situation, a monthly arrangement could potentially feel more comfortable if the relevant policy offers it.
But if the entrepreneur prefers to reserve the annual amount from business profits and keep insurance separate from operating cash, yearly payment might work better.
Again, the answer depends on the individual situation and actual policy terms.
🔷 Which Insurance Premium Payment Option Is Right for You?
Instead of asking, “Which payment option is best for everyone?” ask these questions.
🔷Monthly may suit you if:
🔸Your income arrives regularly each month.
🔸You prefer predictable recurring expenses.
🔸You want to spread payments across the year.
🔸You already follow a detailed monthly budget.
🔸A large one-time payment would affect your liquidity.
🔸You are comfortable managing recurring payment dates.
Yearly may suit you if:
🔸You prefer fewer payment dates.
🔸You plan your finances annually.
🔸You can comfortably reserve the required amount.
🔸You prefer handling insurance as one planned annual expense.
🔸You regularly conduct an annual financial review.
🔸A larger one-time payment would not disrupt your other priorities.
Neither list is a rule.
It is simply a decision-making guide.
🔷 Can High-Income Families Benefit From Monthly Insurance Payments?
Yes, potentially.
Having a high income does not automatically mean that yearly payment is better.
A high-income family may have significant commitments involving:
🔸children's education
🔸property
🔸investments
🔸business interests
🔸retirement planning
🔸travel
🔸lifestyle expenses
🔸family support
🔸emergency reserves
For such families, monthly payments may sometimes make cash-flow management easier.
On the other hand, a financially established family with strong liquidity may prefer the simplicity of a yearly payment.
The best payment frequency is the one that fits the family's financial system without creating unnecessary pressure.
🔷 Before Choosing a Payment Frequency, Ask These Questions
Before purchasing or changing an insurance payment plan, speak with an advisor and ask:
🔸What payment frequencies are 🔸available for this specific policy?
🔸What is the total premium payable?
🔸Does the payment frequency change the total amount payable?
🔸Are there any applicable charges or conditions?
🔸What are the payment due dates?
🔸What happens if a payment is missed or delayed according to the policy terms?
🔸What benefits and coverage does the policy provide?
🔸How does the policy fit my family's financial goals?
🔸Who should I nominate as the beneficiary or nominee, according to the applicable policy process?
🔸Can the payment arrangement be changed later, and under what terms?
These questions can turn a confusing insurance decision into a much clearer financial discussion.
🔷 How National Life Insurance PLC Can Help
Choosing between monthly and yearly insurance premium payments should begin with understanding your family's needs.
National Life Insurance PLC can be a useful place to start that conversation if you want to explore life insurance options, family protection needs, premium payment arrangements and suitable policy choices.
Depending on your goals, you may want to learn more about areas such as:
🔸Child Insurance
🔸Pension Policy
🔸DPS
🔸Whole Life Insurance
🔸Islami Takaful
🔸Group Insurance
The exact payment frequency, premium amount, eligibility and policy conditions should always be confirmed for the specific product and policy you are considering.
For example, a parent planning for children's future needs may have different priorities from a business owner planning long-term family protection. Similarly, someone thinking about retirement may approach insurance differently from an employer considering group insurance.
That is why a conversation with an insurance advisor can be more useful than simply choosing a payment frequency based on what a friend or relative does.
🔷 Monthly vs. Yearly Insurance Premium: The Smart Way to Decide
If you remember only one thing from this guide, remember this:
Do not choose a payment frequency simply because it sounds cheaper, easier or more popular. Choose it after understanding your actual policy terms and your own financial cash flow.
Monthly payments can offer budgeting convenience.
Yearly payments can offer simplicity.
Neither one automatically wins.
The better option is the one that helps you maintain your insurance commitment comfortably while fitting into your wider financial plan.
For a high-income family, this can be particularly important. A strong income does not eliminate the need for financial organization. In fact, as income and financial responsibilities grow, managing cash flow thoughtfully often becomes even more important.
Insurance should fit into that larger picture.
🔷 Talk to an Insurance Advisor
Still unsure whether monthly or yearly insurance premium makes more sense for your family?
You do not have to make the decision alone.
Talk to a National Life Insurance PLC insurance advisor about your family's financial priorities, protection needs, available insurance options and applicable premium payment arrangements.
Ask for the actual premium schedule and policy terms before making your decision.
A good insurance decision is not simply about choosing between twelve payments and one payment.
It is about choosing a plan that makes sense for your family, your cash flow and your long-term financial goals.
🔷 Common Mistakes to Avoid When Choosing an Insurance Payment Plan
Before choosing monthly or yearly insurance premium payments, avoid making a decision based on only one factor.
Do not assume that yearly payment is always cheaper. The actual cost depends on the policy's premium structure and applicable terms.
Do not assume that monthly payment is always more affordable. A smaller individual payment can still represent a significant annual commitment.
Do not compare only the instalment amount. Look at the total premium payable.
Do not ignore your long-term cash flow. An option that looks convenient today should also remain manageable as part of your financial planning.
Do not choose a payment frequency without understanding the policy terms. Ask an authorized insurance professional to explain the applicable conditions before making your decision.
🔷 A Simple 5-Step Decision Guide
If you are still unsure whether monthly or yearly insurance premium payments are right for you, follow these five steps:
Step 1: Review your income.
Understand when and how your income normally arrives.
Step 2: Review your expenses.
Consider household expenses, education costs, business commitments, savings and other financial responsibilities.
Step 3: Compare the total premium.
Do not judge the option only by the monthly or yearly payment amount.
Step 4: Check the policy terms.
Understand the applicable payment frequency, premium structure and other relevant conditions.
Step 5: Get professional guidance.
If you are uncertain, speak with an insurance advisor and request a premium calculation based on your needs.
🔷 Frequently Asked Questions
1. Is monthly or yearly insurance premium better?
Neither option is universally better. Monthly payments may suit people who prefer spreading expenses across regular income, while yearly payments may suit people who prefer one planned annual commitment. The right choice depends on your cash flow, budgeting habits, policy terms and the total amount payable.
2. What is the difference between monthly and yearly insurance premiums?
A monthly insurance premium is paid according to a monthly payment schedule, while a yearly insurance premium is paid once annually according to the policy terms. The main practical difference is how the payment fits into your cash flow and financial planning.
3. Is yearly insurance cheaper than monthly insurance?
Not necessarily. You should never assume that yearly insurance is automatically cheaper. The total cost depends on the specific insurance policy and applicable terms. Compare the total premium, payment frequency, charges if applicable, benefits and policy conditions before deciding.
4. Can I pay life insurance premiums monthly?
Some insurance policies may provide different payment frequency options, but availability depends on the specific product and policy terms. If you prefer monthly insurance payments, ask National Life Insurance PLC or an authorized advisor whether the policy you are considering supports that payment arrangement.
5. What are the benefits of monthly insurance payments?
Monthly payments may make budgeting easier for people with regular monthly income because the expense can be incorporated into their recurring household budget. They may also help avoid arranging a larger one-time payment, although the exact terms and total payable amount should always be checked.
6. What are the benefits of yearly insurance payments?
Yearly insurance payments can be convenient for people who prefer fewer payment dates and annual financial planning. They may suit financially established individuals who can comfortably reserve the required amount in advance. However, the actual payment terms should be confirmed for the specific policy.
7. Does payment frequency affect insurance cost?
It can depend on the specific policy and insurer's terms. Payment frequency should therefore be evaluated alongside the total premium payable, applicable charges if any, policy benefits and other conditions. Do not assume that changing from monthly to yearly automatically reduces or increases the total cost.
8. Which insurance premium payment option is better for families?
The better option depends on the family's financial habits. Families with regular monthly cash flow may prefer monthly payments, while families that plan major financial commitments annually may prefer yearly payments. The decision should be based on affordability, convenience and the specific policy terms.
9. Can high-income families benefit from monthly insurance payments?
Yes. High-income families can still prefer monthly payments if they have substantial recurring commitments such as education, investments, property expenses and business responsibilities. Monthly payment may help them manage cash flow. However, a family with strong liquidity may also prefer the simplicity of yearly payment.
10. Should I choose monthly or yearly insurance for my first policy?
As a first-time buyer, focus on understanding the policy before choosing a payment frequency. Review the coverage, total premium, payment schedule, benefits, conditions and your family's financial priorities. Speaking with an insurance advisor can help you understand the available options before making a commitment.
11. What should I compare before choosing an insurance payment plan?
Compare the total premium payable, payment frequency, applicable charges if any, payment dates, policy benefits, coverage and relevant terms. Also consider your monthly cash flow and ability to maintain payments over time. The cheapest-looking payment is not necessarily the most suitable one for your situation.
12. Is monthly insurance payment more flexible?
Monthly payment can feel more flexible for people who prefer distributing expenses across the year. However, actual flexibility depends on the policy's terms. Before choosing a monthly insurance payment, confirm the available payment frequency, due dates and any applicable conditions with the insurer or advisor.
13. Is yearly insurance payment better for business owners?
It depends on the business owner's cash-flow pattern. Someone with predictable annual liquidity may prefer yearly payment, while someone who wants to manage recurring household expenses alongside variable business cash flow may prefer a different arrangement if available. The decision should be based on actual financial circumstances.
14. How do I choose the right insurance payment frequency in Bangladesh?
Start by reviewing your income pattern, household expenses, emergency fund, financial commitments and insurance goals. Then compare the actual monthly and yearly payment terms available for the policy. For Bangladesh-based families, discussing the options with an authorized National Life Insurance advisor can help clarify the decision.
15. Where can I get help choosing an insurance payment option?
You can speak with a National Life Insurance PLC insurance advisor about your insurance needs, available policy options and applicable payment arrangements. Ask the advisor to explain the total premium, payment frequency, benefits and policy-specific terms before you make a decision.
16. Can I switch from monthly to yearly insurance payments?
Answer:
Whether you can change your premium payment frequency depends on the specific policy and its applicable terms. If you are considering a change, contact National Life Insurance PLC or an authorized advisor and ask about the available options, conditions and any applicable requirements.
17. Should I choose payment frequency based on premium amount alone?
Answer:
No. Premium amount is important, but it should not be the only factor. You should also consider coverage, policy benefits, payment terms, your cash flow, financial commitments and your ability to maintain the payment arrangement over time.
← Back to Insights
NLI Archive / 2026
Trending Analysis
Monthly vs. Yearly Insurance Premium: Which Is Better?
N
NLI Editorial
© National Life Insurance Co. Ltd.
Share:
FB
LN