Insurance Planning After Marriage in Bangladesh: 10 Essential Steps to Protect Your Family’s Financial Future
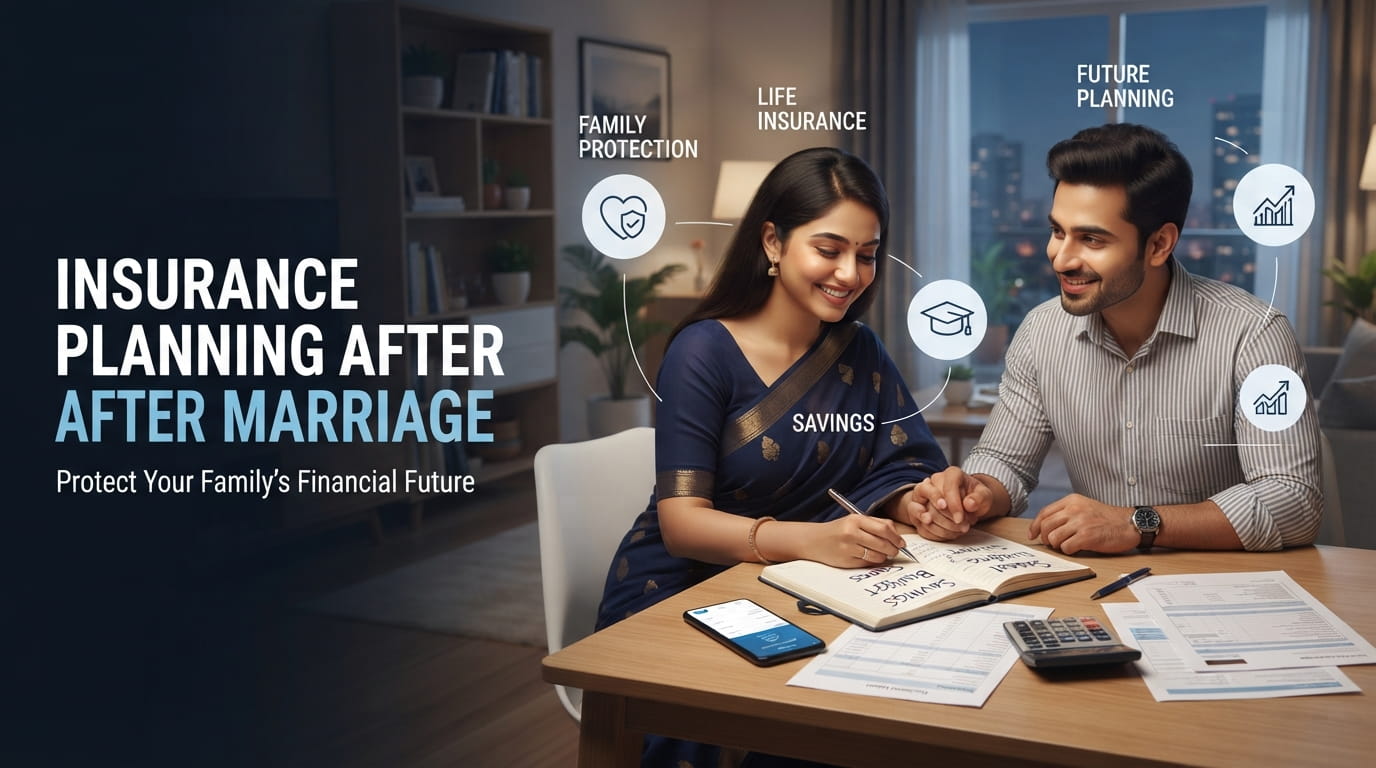
Imagine a newly married couple sitting together at the end of the month.
The wedding celebrations are over. এখন সামনে নতুন সংসার—বাসা ভাড়া, বাজার খরচ, utility bills, transportation, family support and monthly savings. At first, their financial discussion is mostly about managing today.
Then a bigger question comes up:
“If something changes in our family or one of us can no longer contribute financially, are we prepared?”
It is a thoughtful question—not a fearful one.
Marriage often changes the way adults think about money. আপনার spouse may become financially dependent on your income, or both partners may contribute to the household. Later, children, education expenses, parental responsibilities, housing costs and retirement planning may become part of the same financial picture.
That is where insurance planning after marriage in Bangladesh can become relevant.
Insurance should not be viewed as a substitute for every other financial arrangement. বরং, it can be considered as one part of a broader plan that may also include emergency savings, regular savings, long-term goals and retirement preparation.
Most importantly, there is no single insurance plan that is automatically suitable for every married couple.
Your income, expenses, dependants, existing savings, financial obligations, goals, affordability and the exact terms of a policy all matter.
So instead of asking only, “Which insurance should I buy after marriage?”, start with a more useful question:
“What financial responsibilities do we have, what protection might we need, and how could insurance fit into our overall plan?”
🔷 What Is Insurance Planning After Marriage in Bangladesh?
Insurance planning after marriage means reviewing your financial protection needs as your family responsibilities change and considering suitable insurance alongside savings and other long-term financial goals.
বিয়ের পর আপনার financial situation may look different from what it was when you were single. Your spouse may depend on your income, both partners may contribute to household expenses, or you may continue supporting parents or other family members.
Future children can also introduce new goals, including education, healthcare, daily living costs and long-term financial support.
In practical terms, insurance planning means first understanding your responsibilities and then reviewing insurance options based on factors such as:
🔸Coverage or protection
🔸Premium and payment requirements
🔸Policy duration
🔸Sum assured
🔸Benefits
🔸Eligibility
🔸Exclusions
🔸Maturity-related conditions
🔸Other applicable policy terms
It is therefore more than simply purchasing a policy.
Good insurance planning starts with understanding your family—not with choosing a product name.
🔷 Why Does Insurance Planning Matter After Marriage?
Marriage can turn individual financial decisions into shared family decisions.
Before marriage, someone may mainly think about personal expenses, career development and individual savings. After marriage, however, one person's financial decisions can directly affect another person's financial stability.
একজন newly married adult may suddenly have several responsibilities at the same time:
🔸Shared household expenses
🔸A spouse who depends partly or fully on income
🔸Support for parents or other dependants
🔸Existing loans or financial commitments
🔸Future child-related expenses
🔸Long-term savings goals
🔸Retirement planning
This does not mean every married person needs the same level of insurance.
বরং, marriage is a natural time to review your financial position.
A simple review can help answer:
Who depends on my income?
What expenses would continue if my income were interrupted?
What financial goals are we working toward?
What protection do we already have?
What gaps, if any, should we discuss?
That is a more practical approach to family financial planning than buying insurance simply because you have recently married.
🔷 10 Essential Steps for Insurance and Financial Planning After Marriage
1. Review Your New Financial Responsibilities
The first step is not choosing an insurance policy.
First, understand what has changed.
Sit together and discuss your household's monthly financial picture. Rent or housing costs, food, transportation, utilities, family support, savings and existing obligations can all be part of the conversation.
একসঙ্গে বসে একটি simple but realistic monthly picture তৈরি করুন:
🔸How much income comes into the household?
🔸Which expenses are essential?
🔸How much can realistically be saved?
🔸Does either spouse support parents or other dependants?
🔸Are there existing loans or financial commitments?
🔸What major financial goals may arise over the next 5–15 years?
This conversation can reveal something important: your financial priorities after marriage may be different from your priorities before marriage.
For example, a person who previously saved mainly for personal goals may now want to build a shared emergency fund or think about family protection.
In practice: Start your insurance review with a household budget and responsibility check.
2. Understand Who Depends on Your Income
Not every married family has the same structure.
Some couples are dual-income households. Some families rely mainly on one income. Some spouses support parents, siblings or other relatives alongside their own household.
তাই “dependant” বলতে শুধু spouse বা future children বোঝায় না। Anyone whose essential financial needs depend significantly on your income may be relevant to your planning.
Consider a newly married professional whose spouse is currently not earning.
If most household expenses depend on that one income, the couple may reasonably want to understand what financial protection could be available if that income were unexpectedly lost, subject to the terms of any policy they consider.
A dual-income couple may have a different financial position because both partners contribute to household income.
Neither situation is automatically better or worse. The important thing is to understand the dependency.
A useful question to ask
If one income became unavailable, which essential family expenses would still need to be paid?
The answer can help you think more clearly about the role of life insurance and other financial resources.
In practice: Identify who depends on each spouse's income before estimating protection needs.
3. Estimate Your Family's Financial Protection Needs
There is no universal number that every married person should insure.
A realistic assessment should consider your own financial circumstances.
Think about:
🔸Current household expenses
🔸Income contribution from each spouse
🔸Existing debts or obligations
🔸Support provided to parents or other dependants
🔸Future education-related goals
🔸Long-term family plans
🔸Existing savings
🔸Other available financial resources
For example, imagine two families.
Family A has two stable incomes, substantial savings and relatively few dependants.
Family B relies heavily on one income, has limited savings and supports several family members.
Their financial protection needs may be quite different.
আপনার লক্ষ্য হওয়া উচিত একটি arbitrary coverage number খুঁজে বের করা নয়। বরং, যদি কোনো income-generating family member মারা যান বা a covered event occurs, তাহলে family-এর financial position কীভাবে affected হতে পারে—সেটা বোঝা।
Of course, any actual insurance benefit depends on the selected policy's terms and applicable conditions.
In practice: Estimate your potential financial gap rather than copying someone else's coverage amount.
4. Consider Life Insurance as Part of Family Protection
Life insurance can be one component of a family's financial protection strategy.
In simple terms, a life insurance policy may provide specified benefits when a covered event occurs, subject to the policy's terms, conditions, exclusions and applicable requirements.
Some insurance products also include savings or maturity-related features.
But there is an important distinction:
Insurance protection and savings-related benefits are not automatically the same thing.
একটি policy-তে savings বা maturity benefit থাকলেই সেটি ordinary savings account-এর মতো কাজ করবে—এমন assumption করা ঠিক নয়।
The policy document determines the actual premium requirements, benefits, maturity conditions, exclusions and other provisions.
National Life Insurance PLC's published product portfolio includes categories such as endowment insurance, child protection, pension-related products, whole life, monthly savings, education security and Takaful products.
That variety means a reader can explore different categories according to different financial objectives—but it does not mean one product is suitable for every family.
Before considering any policy, ask:
🔸Who is protected?
🔸What event triggers the applicable benefit?
🔸How long does the policy continue?
🔸What payments are required?
🔸What conditions and exclusions apply?
In practice: Evaluate life insurance by its actual protection and policy terms—not by its headline name alone.
5. Connect Insurance With Your Savings Goals
A common mistake after marriage is treating insurance and savings as if they solve exactly the same problem.
They do not.
Insurance can address specified protection needs according to policy terms. Savings can help create financial reserves for planned or unexpected expenses.
একটি practical financial plan may therefore consider different tools for different purposes:
🔸Emergency savings → short-term financial resilience
🔸Insurance → specified protection and policy-related benefits
🔸Long-term savings → future financial goals
🔸Retirement planning → future income needs
The exact balance depends on your circumstances.
For example, a couple may decide to maintain an emergency fund while separately reviewing their life insurance needs. Another couple may have a long-term education goal and explore an appropriate savings-oriented insurance option.
National Life Insurance PLC's published portfolio includes Monthly Savings Insurance, Family Savings & Income Insurance Plan and other savings-related products. Its 2024 Annual Report also identifies ordinary life insurance, Takaful, pension-related, group and microinsurance categories.
তবে product category দেখেই সিদ্ধান্ত নেওয়া উচিত নয়। আপনার affordability, goals এবং exact policy terms আগে বুঝতে হবে।
In practice: Give insurance and savings clearly defined roles within the same financial plan.
6. Think About Future Children and Education
For many Bangladeshi couples, children eventually become an important part of financial planning.
Even before having a child, you may think about future education, healthcare, daily expenses and long-term support.
Imagine a couple who has recently married and hopes to have children in the next few years.
তারা আজ থেকেই একটি simple financial habit তৈরি করতে পারে—regular savings, realistic budgeting and periodic review of their financial protection.
The goal is not to predict the exact cost of education years in advance.
বরং, লক্ষ্য হলো future responsibility-এর জন্য early preparation শুরু করা।
When children become part of the family, review the plan again. Your income dependency, savings goals and protection needs may have changed.
National Life Insurance PLC's published 2024 product portfolio includes a Child Protection Policy and Children Education Security Plan, among other child-focused products. Whether a particular product is appropriate depends on the family's circumstances and the policy's official terms.
In practice: Treat future children as a planning consideration, not as a reason to make a rushed financial decision.
7. Review Your Long-Term Financial Goals
Marriage is about more than managing this month's expenses.
It can also be a useful time to discuss where you want your family to be 10, 15 or 20 years from now.
আপনাদের long-term conversation হতে পারে:
🔸Where do we want to live?
🔸How will we prepare for children's education?
🔸What major purchases may be needed?
🔸How much should we aim to save?
🔸How will we prepare for retirement?
🔸Which family responsibilities may increase?
🔸How can both spouses remain financially prepared?
🔸Long-term planning does not require perfect predictions.
Income changes. Career paths change. Family responsibilities change.
তাই insurance planning-ও static হওয়া উচিত নয়।
National Life Insurance PLC's published portfolio includes pension-related products such as Pension Insurance, Assurance Cum Pension Policy and National Pension Deposit Insurance.
These categories may be relevant to people considering different long-term financial goals, but suitability should always be assessed individually.
In practice: Think beyond the wedding year and consider the financial life you want to build together.
8. Understand Policy Terms Before Choosing a Plan
This may be the most important practical step.
একটি policy শুধু নাম, premium বা advertised benefit দেখে choose করবেন না।
Before making a long-term commitment, understand:
🔸Premium or payment requirements
🔸Policy term
🔸Sum assured
🔸Eligibility
🔸Benefits
🔸Maturity-related conditions
🔸Exclusions
🔸Payment schedule
🔸Nominee-related provisions
🔸Surrender or discontinuation conditions
🔸Other applicable policy rules
Suppose a policy mentions a maturity benefit.
Do not assume that the amount, timing or conditions are the same as another policy. Read the official documentation and ask how the benefit actually works.
Similarly, if a policy provides a protection benefit, understand exactly what event is covered and which exclusions or conditions may apply.
National Life Insurance PLC's own published guidance also recommends checking premium, policy term, benefits, conditions and exclusions and confirming the latest policy information before purchase.
In practice: If you do not understand a policy term, ask before signing—not after purchasing.
9. Reassess Your Plan as Your Family Changes
Insurance planning after marriage should not end when the policy is purchased.
Your financial situation can change significantly over time.
You may need to review your plan when:
🔸You have a child
🔸Your income increases or decreases
🔸You change careers
🔸Your spouse starts or stops working
🔸You take on a major financial obligation
🔸You begin supporting another dependant
🔸Your savings position changes
🔸Your long-term goals change
ধরুন, marriage-এর সময় দুজনেই income করতেন। কয়েক বছর পরে একটি সন্তান হলো এবং একজন spouse temporarily কাজ থেকে বিরত থাকলেন।
Now the household's income dependency has changed.
That does not automatically mean a new policy is required. It simply means the family should review whether its existing financial arrangements still reflect its current responsibilities.
In practice: Major life events are natural moments for a financial and insurance review.
10. Build a Practical and Sustainable Protection Strategy
The final step is balance.
A financial plan only works when you can realistically maintain it over time.
আপনার insurance premium যদি household budget-এর ওপর excessive pressure তৈরি করে, তাহলে long-term sustainability নিয়ে ভাবতে হবে। At the same time, ignoring financial protection completely may leave important responsibilities insufficiently planned.
Think about five things together:
Affordability + protection needs + financial goals + policy terms + long-term consistency
Do not choose a policy simply because someone describes it as “the best.”
A plan that works for a dual-income couple may not work for a single-income household. A young couple without children may have different priorities from parents supporting several dependants.
National Life Insurance PLC's 2024 Annual Report lists a broad range of products across ordinary life insurance, Takaful, pension, group and microinsurance, while its current company profile lists 705 branches and states that the company commenced operations on 23 April 1985.
This range provides categories to explore, but the existence of multiple products should not be interpreted as evidence that one particular product is suitable for everyone.
In practice: Choose only after you understand both your family's needs and the policy's actual terms.
🔷 Insurance and Savings: How Should They Work Together?
Many newly married couples ask:
“Should we save first, or should we get insurance first?”
There is no universal answer.
The better approach is to understand what each financial arrangement is intended to do.
Insurance can provide specified protection according to policy terms.
Savings can build accessible financial reserves for planned or unexpected needs.
For example, an emergency fund may help with a sudden household expense. A life insurance policy may address specified protection needs if a covered event occurs. A long-term savings arrangement may support a future financial goal.
একটি ভালো financial plan therefore does not necessarily choose “insurance versus savings.” It considers how different financial tools can serve different purposes.
And if a policy includes maturity or savings-related benefits, do not treat those benefits as identical to liquid cash savings.
Always review the actual policy documentation before making assumptions about amounts, timing or availability.
🔷 Life Insurance and Family Financial Protection
After marriage, life insurance can become especially relevant when another person depends significantly on your income.
Consider a young couple where one spouse is the primary earner.
Monthly housing costs, food, utilities, family support and future plans may all depend substantially on that income.
In that situation, the couple may want to understand what financial resources could be available if the primary earner dies, subject to the terms of any selected policy.
But good planning requires more than asking, “How much is the premium?”
Ask:
🔸Who is protected?
🔸Who is the nominee?
🔸What event triggers the benefit?
🔸How long does the policy continue?
🔸What premium must be paid?
🔸What benefits are contractual?
🔸What exclusions apply?
🔸What happens if payments stop?
🔸What happens at maturity?
🔸Does the policy align with the family's goals?
এই questions-এর উত্তর clear না হলে decision নেওয়ার আগে explanation নেওয়া উচিত।
The objective is not simply to own an insurance policy.
The objective is to understand what financial protection that policy is actually designed to provide.
🔷 Takaful and Islamic Insurance Considerations in Bangladesh
For some Bangladeshi families, Shariah-oriented financial planning is an important consideration.
Takaful is an Islamic insurance-related model designed around Shariah-oriented principles. Anyone considering a Takaful product should understand its structure, payment requirements, benefits and conditions from the relevant official documentation.
National Life Insurance PLC's published 2024 product portfolio includes:
🔸Takaful Three Payments Bima
🔸Takaful Four Payments Bima
🔸Takaful One Payment Endowment Policy
🔸Takaful Monthly Savings Insurance
The same annual report identifies Islami Takaful Bima as one of the company's insurance segments.
তবে শুধু “Takaful” নাম দেখেই কোনো policy সম্পর্কে assumption করা উচিত নয়।
Read the applicable documents carefully and ask an authorized representative to explain any term you do not understand.
The right question is not simply “Is this Takaful?” but “How does this particular product work, and what are its actual terms?”
🔷 4 Practical Newlywed Financial Planning Examples
Example 1: A Dual-Income Couple
ধরুন, দুজনেই চাকরি করেন এবং household expenses share করেন। They have no children yet and want to build savings.
Their first step could be understanding their combined income, essential expenses, emergency savings and existing insurance.
After that, they can review whether their current protection arrangements still make sense after marriage.
Lesson: Marriage is a reason to review financial protection—not automatically a reason to increase it.
Example 2: A Single-Income Household
Imagine a newly married household where one spouse is currently the primary income earner.
The other spouse may depend significantly on that income for housing, food, utilities and other essential expenses.
The couple may therefore want to examine how their finances would be affected if that income were unexpectedly lost.
Lesson: Income dependency is an important factor when thinking about family protection.
Example 3: Planning for Children
একটি couple এখন সন্তান নেওয়ার planning করছে। They start putting money aside regularly while also reviewing their existing insurance.
They do not try to predict every future expense.
Instead, they establish a habit of saving, discuss education goals and plan to review their financial arrangements when their family changes.
Lesson: Start with the goal, then choose financial tools that genuinely support it.
Example 4: Changing Responsibilities
Suppose a couple's income increases and they later take on a major financial obligation, such as a home-related commitment or additional family support.
Their original financial plan may no longer reflect their current situation.
They can review their savings, insurance, dependants and long-term goals again.
Lesson: Financial planning should evolve as your responsibilities evolve.
🔷 How National Life Insurance PLC Can Fit Into Your Planning
National Life Insurance PLC has operated in Bangladesh since 23 April 1985. Its current official company profile lists 705 branches, while its 2024 Annual Report states that life insurance services were being provided through 705 business points across the country.
Its published product portfolio includes a range of categories, including:
🔸Endowment Insurance
🔸Child Protection Policy
🔸Children Education Security Plan
🔸Pension Insurance
🔸Whole Life Policy
🔸Monthly Savings Insurance
🔸Assurance Cum Pension Policy
🔸Takaful products
🔸Group insurance
🔸Microinsurance
🔸National Pension Deposit Insurance
These categories are documented in National Life Insurance PLC's 2024 Annual Report.
For a newly married person, however, the most important point is not that one category is automatically suitable.
বরং, আগে নিজের financial situation বুঝুন।
Then consider:
🔸Your age and income
🔸Household responsibilities
🔸Dependants
🔸Existing savings
🔸Financial obligations
🔸Future goals
🔸Desired protection period
🔸Premium affordability
🔸Savings or maturity objectives
🔸Policy conditions and exclusions
For example, someone thinking primarily about children's future may explore child-focused options. Someone thinking about retirement may investigate pension-related products. A person seeking Shariah-oriented insurance may explore Takaful categories.
But these are starting points for discussion—not recommendations that one product is suitable for every person.
National Life Insurance PLC's official website provides company and product information, and its published guidance advises readers to confirm current premium, eligibility, product availability and policy terms before making a decision.
If you want to explore your options, you can review the official information and discuss your circumstances with an authorized representative or visit a National Life Insurance PLC branch.
🔷 Key Questions to Ask Before Choosing an Insurance Plan
Before making a long-term commitment, write down your questions.
🔷Ask about the policy
🔸What is the main purpose of this policy?
🔸Who is covered?
🔸Who can be nominated?
🔸What is the policy term?
🔸What is the sum assured?
🔸What premium must I pay?
🔸How frequently must I pay?
🔷 Ask about the benefits
🔸What benefits are included?
🔸When are the benefits payable?
🔸Is there a maturity-related benefit?
🔸Which benefits depend on specific conditions?
🔸What happens if a covered event occurs during the policy term?
🔷 Ask about conditions
🔸What exclusions apply?
🔸What happens if I miss or stop payments?
🔸What are the surrender conditions?
🔸What eligibility requirements apply?
🔸Where can I read the full policy terms?
🔷 Ask yourself
🔸Can I comfortably maintain the premium?
🔸Does this policy support an actual financial goal?
🔸Have I understood the conditions?
🔸 Would this plan still make sense if my family circumstances changed?
These questions help you move from:
“I need insurance.”
to:
“I understand what financial arrangement I am considering and why.”
🔷 Frequently Asked Questions
1. What is insurance planning after marriage in Bangladesh?
Insurance planning after marriage means reviewing family responsibilities, dependants, financial goals and protection needs before considering suitable insurance arrangements.
2. Why is insurance important after marriage?
Marriage can create shared financial responsibilities. Insurance may provide specified financial protection when covered events occur, subject to policy terms.
3. What insurance should newly married couples consider?
Couples should first assess income, dependants, goals and affordability before exploring life, savings-oriented, child-focused, pension or Takaful options.
4. Is life insurance necessary for every married couple?
No. The relevance of life insurance depends on income dependency, financial obligations, existing resources, goals and the specific policy.
5. How should couples plan insurance in Bangladesh?
Couples can review responsibilities, identify dependants, assess protection needs, understand policy terms and consider affordable arrangements that support their goals.
6. Should insurance and savings be planned together?
They can be considered together because they serve different purposes. Insurance addresses specified protection needs, while savings build financial reserves.
7. When should newly married couples review insurance?
Review after marriage and again following major changes such as children, income changes, new obligations, career changes or additional dependants.
8. Does National Life Insurance PLC offer child-related insurance?
Yes. Its published portfolio includes Child Protection Policy and Children Education Security Plan, subject to their respective policy terms.
9. Does National Life Insurance PLC offer Takaful?
Yes. Its published portfolio includes Takaful Three Payments Bima, Four Payments Bima, One Payment Endowment Policy and Monthly Savings Insurance.
10. Can insurance support long-term financial planning?
Certain policies may include protection, savings, maturity or pension-related features. Exact benefits depend on the selected policy and its official terms.
11. What should I check before buying insurance after marriage?
Check premium requirements, policy duration, sum assured, benefits, exclusions, eligibility, payment conditions and maturity-related provisions before committing.
12. Is there one ideal insurance plan for every family?
No. Families have different incomes, responsibilities and goals. Suitability depends on individual circumstances and the exact policy conditions.
13. Should both spouses review their insurance?
Yes. Both spouses can review income contributions, dependants, existing protection, savings and financial goals to understand their current position.
14. Can insurance planning change after having children?
Yes. Children can introduce additional responsibilities such as education and living expenses, making a review of protection and savings useful.
15. Where can I discuss insurance planning with National Life Insurance PLC?
You can review official information and contact National Life Insurance PLC through its published channels or visit a branch to discuss your requirements.
🔷 Conclusion: Marriage Is a New Financial Chapter
Think back to the couple we imagined at the beginning.
Their first financial conversations may have been about rent, groceries, utility bills and monthly savings.
Over time, those conversations may become bigger.
Children. Education. Parents. Housing. Retirement. Long-term financial security.
That is why insurance planning after marriage in Bangladesh is not simply about buying a policy.
It is about taking a step back and understanding how your financial responsibilities have changed.
বিয়ের পর সবচেয়ে useful financial conversation হতে পারে খুব simple:
“If our responsibilities change, are we financially prepared?”
You do not need to have every answer immediately.
Start by understanding your household income and expenses. Identify who depends on each income. Review your existing savings and insurance. Think about future goals. Then, if insurance appears relevant, study the available options and their actual policy terms carefully.
Remember, a policy should not be selected simply because someone calls it “the best.” A sustainable financial decision is one that you understand, can maintain and believe is relevant to your family's circumstances.
National Life Insurance PLC provides a range of life insurance and Takaful-related products in Bangladesh, and its official information can be reviewed when exploring possible options.
If you would like to understand which type of insurance arrangement may fit your financial situation, visit a National Life Insurance PLC branch or speak with an authorized representative. Take your questions with you, review the official policy documents and make your decision based on your family's actual needs.
Marriage begins a new chapter.
And thoughtful financial planning can help you approach that chapter with greater clarity, responsibility and confidence.
← Back to Insights
NLI Archive / 2026
Trending Analysis
Insurance Planning After Marriage in Bangladesh
N
NLI Editorial
© National Life Insurance Co. Ltd.
Share:
FB
LN